Business Loans

in Singapore

A business loan is financing provided to your company rather than to you personally, used for cash flow, growth, or equipment.

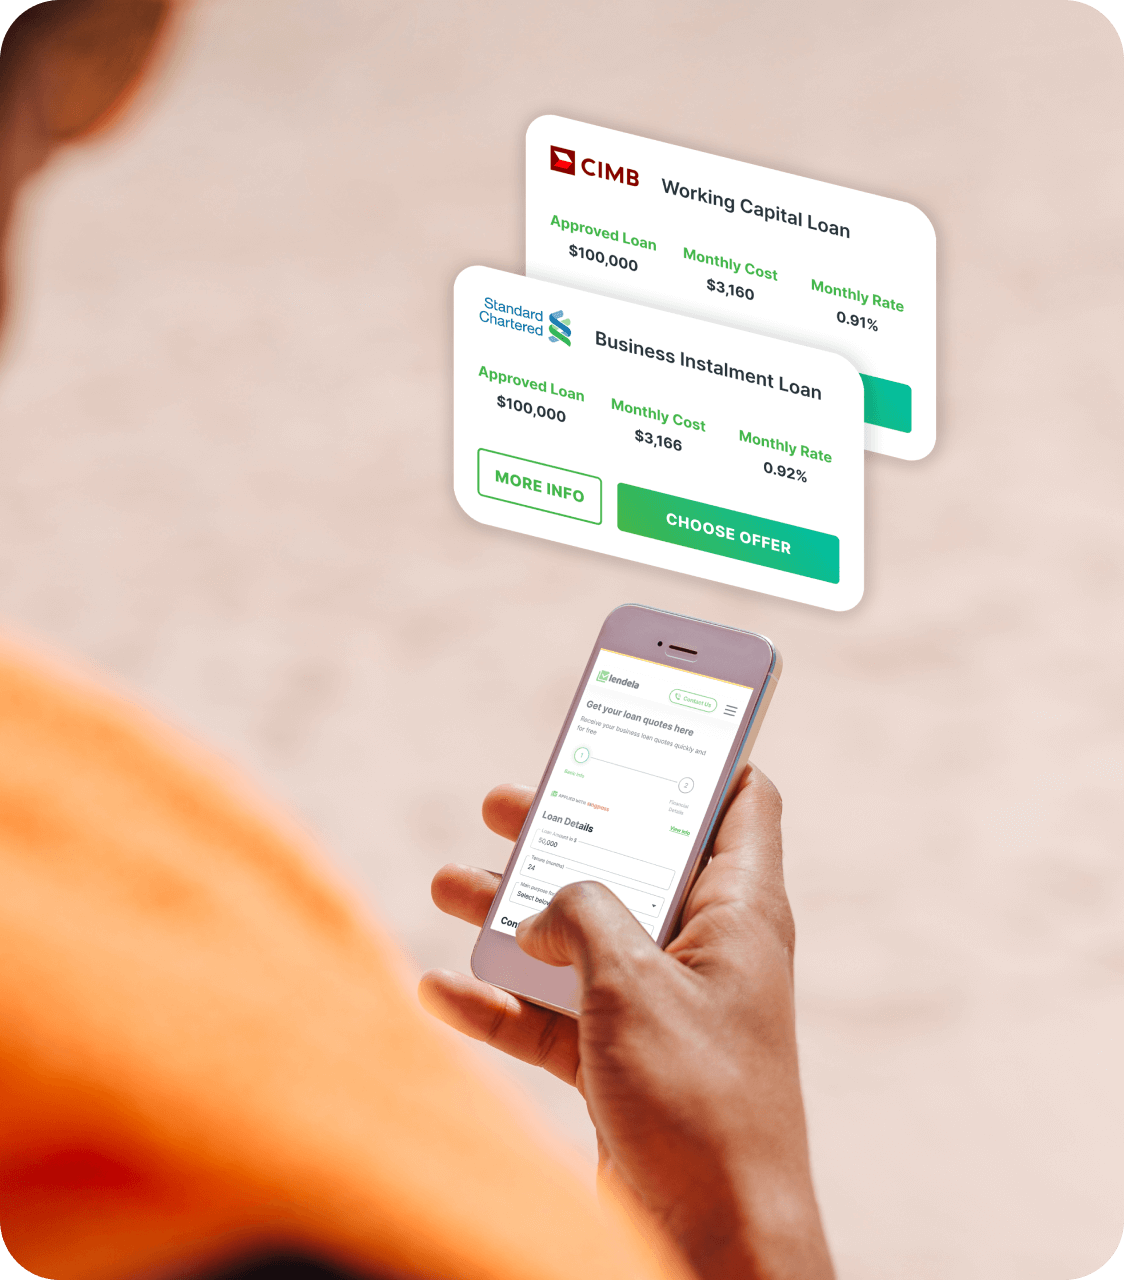
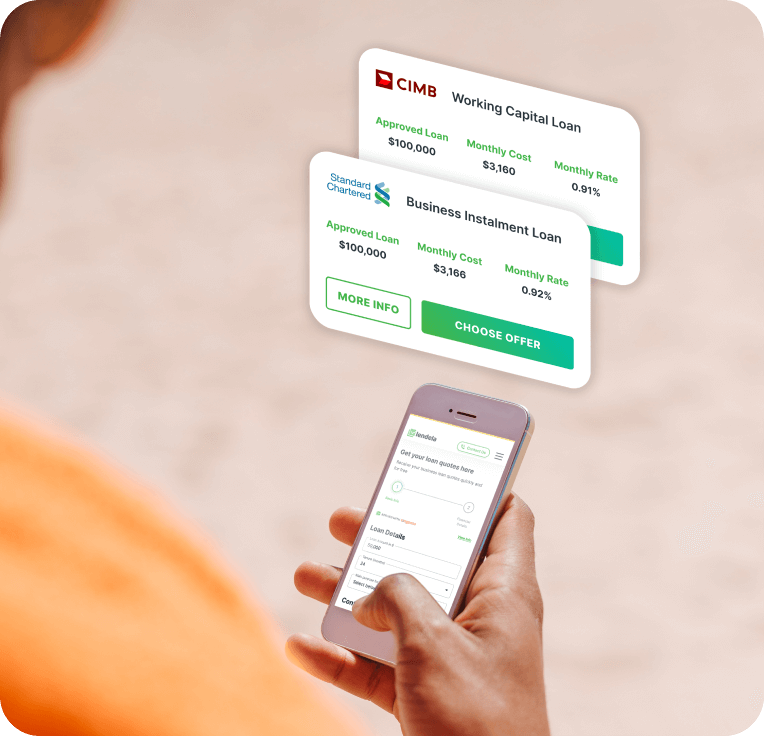
Apply once through Myinfo Business and get matched with offers from 70+ banks and licensed loan providers. Review tenure, fees and total cost side by side.
GET LOAN QUOTES
hero

Supported by:

sfa myinfo
hero

Find an SME loan that fits your business needs

Loan Types

Working capital/term loans

Lump-sum financing for cash flow, payroll, rent, inventory, marketing, and expansion – repaid over a fixed repayment tenure with clear monthly instalments.

Invoice financing solutions

Unlock working capital by financing outstanding invoices – useful when payments are pending and you need to bridge short-term cash flow gaps.

Gov-assisted SME loans

For eligible SMEs, EFS-WCL supports working capital needs. Approval checks may include group annual sales, employment size, and corporate structure.

View all loan types

We work with the best

DBS
POSB
SCB
CIMB Bank
Trust Bank
GXS Bank
UOB
Citibank

How Lendela works

1

Share your business needs

Share your purpose, amount, and company details via Myinfo Business and ACRA retrieval. This helps us match you with the most relevant and competitive offers, with reduced back-and-forth along the process.
2

Review your matched offers

Match with tailored, pre-approved loan offers from banks and financial institutions. See key terms in one view – repayment tenure, fees, and indicative total cost – so you can choose confidently.
3

Proceed with your offer

Choose the most suitable offer and finalise the agreement with the bank to receive your funds. That's it! It’s a simple, guided process designed to make securing your business loan easy and worry-free.

Why businesses choose Lendela

Rated 4.9 out of 5 on Google reviews

google five-stars

2605 Reviews

avatar
Eswaran Kathiravan
1 day ago
Thank you for helping me with my financial a very good help I'm happy
avatar
Toochie Riz
2 days ago
I would like to thank Dharan from Lendela for her unwavering assistance and kindness throughout the process!...
avatar
Noorhayati Nenari
2 days ago
Thanesh have been a great help in assisting my needs and patience with my request. I am really grateful for his...
avatar
haniff khairudin
3 days ago
Previously i engage lendela but still got rejected when i came to the company they recommended. Wasted trip . But...
avatar
Raman Naidu
3 days ago
Lendela has a licensed moneylenders, very good loan assistance, fast response, efficient staff Mr. Dharan who...
avatar
Fat Chin
3 days ago
Very good n efficient no hassle trust me even with bad credit as long as u have good payment u can get a loan
avatar
Noorazlan Roslan
3 days ago
Ms Yamuna is well versed to explain in details of all the process in getting the loan. Good Job... Keep It Up....
avatar
llb
3 days ago
Dharan was very helpful in assisting me in the loan application Good Work
avatar
Tom Tyrone Beiron Tay
3 days ago
Great team that follows up well, and a legit app platform with reputable and reliable partners. Tried the process...
avatar
GeT
3 days ago
Applied through Lendela and was assisted by Thanesh who provided excellent help.
avatar
Fina Haszeman
4 days ago
Yamuna is patient and helpful! Definitely a breeze and smooth transaction
avatar
Ethan Teo
4 days ago
Yamuna was super helpful in guiding and prompt with her replies!

As featured on

the-straits-times e27 money-fm deal-street-asia digital-news-asia banking-and-finance

We’re ready to help you grow your business

Take the first step towards securing funding. Request for loan quotes today.

GET LOAN QUOTES

Speak with an expert

Unsure about the process or have any doubts? We’re happy to share more about the business loan process and structuring.

Frequently Asked Questions

A business loan is financing provided to a company, rather than an individual, to support cash flow, expansion, equipment purchases, or day-to-day operations. In Singapore, this includes unsecured working capital and term loans, government-assisted schemes such as EFS-WCL, invoice financing, and secured facilities such as equipment or commercial property loans.

The right type depends on your business's size, trading history, and what the funds are for. Lendela matches eligible SMEs with 70+ banks and licensed loan providers through a single application.

Businesses commonly consider:

  1. Working capital/term loans (unsecured)

  2. Government-assisted SME loans (e.g. EFS-WCL, if eligible)

  3. Invoice financing

  4. Equipment/machinery financing (secured)

  5. Trade finance

  6. Commercial property loans

EFS-WCL is an Enterprise Singapore scheme that supports SMEs financing operational cashflow needs. Key published criteria include:

  • Entity registered and operating in Singapore

  • At least 30% local equity held directly/indirectly by Singapore citizens/PRs

  • Group annual sales turnover not exceeding $500m

  • For “SME Working Capital”, SME defined as group revenue up to $100m or maximum group employment size of 200

Loan details published by EnterpriseSG include maximum loan quantum $500,000 per borrower, capped at $5,000,000 per borrower group, and maximum repayment period 5 years. Government risk-share is 50%, rising to 70% for young enterprises under 5 years old. This reduces the bank's risk, not what you repay. (Terms apply; final approval is by participating financial institutions.)

For some government-assisted scheme assessments, borrower group definitions can include the borrower, corporate shareholders holding more than 50%, and relevant subsidiaries in the ownership chain. This is why banks and financial institutions may ask for group structure and consolidated figures.

Requirements vary, but common documents include:

  • ACRA BizFile/company profile

  • Directors/guarantors IDs (and shareholding/structure where relevant)

  • Latest 3–6 months business bank statements

  • Latest financial statements (if available)

  • Tax filings/Notices of Assessment (NOAs), where applicable

  • Existing debts schedule (outstanding facilities + monthly obligations)

  • Use-of-funds statement (1–2 paragraphs)

It depends on revenue, profitability, recent bank statements, existing debts, and guarantor strength. For EFS-WCL specifically, EnterpriseSG publishes a maximum loan quantum of $500,000 per borrower, capped at $5,000,000 per borrower group (subject to scheme and bank assessment).

Focus on:

  • Interest pricing (e.g. EIR/APR where applicable)

  • Processing/admin fees

  • Late charges/default interest

  • Early repayment terms

Best practice: compare total payable amount across the same repayment tenure, then read the terms and conditions before acceptance.

With complete documents, expect a few days in general; some digital-first banks and financial institutions can be faster when they handle straightforward cases.

When the financing supports cash-generating investments (such as inventory, working capital gaps, equipment investment, further expansion etc.) and monthly repayments remain sustainable even during slower months.

Yes, startups can apply, but the range of available options may be more limited and interest rates slightly higher, since banks assess risk based on trading history and cash flow.

Under the EFS, “young enterprises” – defined as businesses less than 5 years old, with at least one employee and over 50% individual ownership – may qualify for a higher risk-share of up to 70%.

However, approval still depends on the lender’s credit assessment and documentation review.

Tip: Having clear financial projections and up-to-date bank statements can help strengthen a startup’s loan application.

For company-use funds, business financing keeps liabilities ring-fenced and builds entity banking history. Personal loans can be faster but may blur personal vs. business obligations.

Money questions?
We’ve got answers.

From rate movements to practical money tips, get the updates that keep you informed, whenever they’re worth sharing.

You're subscribed.

We'll send Lendela's money tips and updates to .

whatsapp