How to check your credit score in Singapore

The Lendela Team
October 19th, 2021
Table of contents
- A standard CBS credit report costs $8 before GST, or $8.72 with the current 9% GST.
- You can also get a free credit report when you apply for a new credit facility.
- CBS scores run from 1,000 to 2,000. AA is 1,911 to 2,000 and HH is 1,000 to 1,723.
- Paying debts and bills on time, avoiding many loan applications in a short period, and checking your report for errors help your score over time.
Short answer: you check your credit score by buying your credit report from Credit Bureau Singapore (CBS) online for $8 before GST ($8.72 with the current 9% GST). You also get a free report when you apply for a new credit facility, such as a personal loan.
Did you know that a detailed history of credit payment is on record and accessible by financial organisations, such as banks and insurance, and greatly impacts how they view you as a borrower? This might sound scary, but it is a fact of life in most jurisdictions across the globe.
Well, instead of getting scared, the best thing to do is to learn how credit scoring works and try to stay on the right side of the books. To get things right when it comes to your credit score, you need to start by getting your credit report.
In Singapore, the Credit Bureau Singapore is at the heart of the credit scoring system. It gathers and aggregates data from participating members, from banks to other finance-related firms, to prepare risk profiles of borrowers. Banks and loan providers use this profile to determine the amount they can lend you and the interest to attach to loans. This post digs deeper into credit scores to determine why it is so important, the factors that affect them, and how you can improve yours.
A closer look at your credit score
Your credit behaviour is presented as an aggregated score between 1,000 and 2,000. People on the lowest end of the spectrum, close to 1,000, are rated HH and considered high-risk parties.
Loan providers in Singapore view such people as likely to default on their payments. On the upper end, close to 2,000 points, you will be considered a low-risk party. Therefore, loan providers will be more willing to advance credit to you because they believe you will repay the money without defaulting. CBS groups scores into eight risk grades, from AA (lowest risk) to HH (highest risk):
Risk grade | Score range |
AA | 1,911 to 2,000 |
BB | 1,844 to 1,910 |
CC | 1,825 to 1,843 |
DD | 1,813 to 1,824 |
EE | 1,782 to 1,812 |
FF | 1,755 to 1,781 |
GG | 1,724 to 1,754 |
HH | 1,000 to 1,723 |
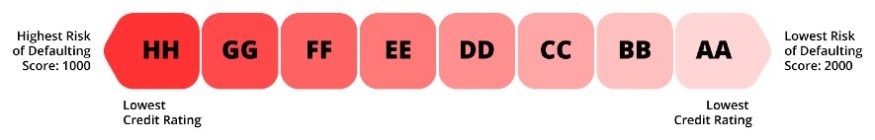
Loan providers in Singapore and across the globe factor the credit score when making their lending decisions for loan applicants. Other important factors that they consider when reviewing loan applications include income, employment status, and litigation information.
Another very important thing about your credit score is that loan providers rely on it when deciding the interest to attach to a loan. If your credit score is rated poorly, loan providers are likely to attach high-interest rates. Some will even decline the loan application unless you provide collateral.
Today, it is not just loan providers who are interested in credit scores. Even employers are now turning to credit bureaus to try and gather more information about potential candidates. Therefore, you are likely to get declined for a job offer even if the papers indicate excellent performance but very poor credit score. Other areas where credit scores will come in handy include insurance and phone contract sectors. So, it would be best if you did everything possible to ensure your score is always good.
Get your credit report and credit score
To get your credit score, you need to get your credit report in Singapore.
How to get your report and score
There are two main methods that you can use to get your credit score: the free method and the paid option. So, which one do you choose?
Pay for your credit report
This is the commonest method that people use to get their credit scores in Singapore. You only need to send a request online from the Credit Bureau Singapore (CBS) to get the report. A standard report costs $8 before GST, which is $8.72 with the current 9% GST, and you can pay online by card.
Get the credit report free
Starting from April 2016, people applying for new credit facilities, whether personal loans or car financing in Singapore or wedding loans are entitled to getting free credit reports. Note that the credit report is provided to you whether the loan is approved or rejected. This initiative is meant to help consumers check and verify their consumers’ ability to verify how complete and accurate the data provided in the report is.
Details included in a credit report
In addition to showing your credit score, the credit report in Singapore will also capture the following information.
Basic personal data, such as telephone numbers and addresses.
A full record of all credit checks about you.
Your credit repayment information over the last 12 months.
Records of default, if any.
Bankruptcy records, if any, in the last five years.
Terminated accounts over the last five years.
The outstanding balances.
Credit limits.
Your credit score.
What to do if you disagree with the report
As we mentioned earlier, the information captured on the credit report and used to calculate your score is sourced from third parties. This means that if one of the parties, such as a bank or insurance company, provides erroneous details about you, the same will go into the report and damage the score. So, if you notice such errors, you need to inform the credit bureau that provided the report. Then, the agency will:
Talk to the bank or insurance that gave the data so that it can provide the correct information.
If any amendments are made to the report, you will be notified about them.
So, go ahead and send the revised credit report with the new score to the bank that you had applied for a loan from.
How to improve your credit score
Now that you know how to check credit scores in Singapore, the next big question might be “How do I improve it?”. We must indicate that it is not a one-time thing nor achievable in haste. Rather, you need to plan well, especially ensuring all the debts you take are cleared on time. So, here are some useful tips to help you improve your score and maintain it at its best:
Make sure to pay your debts on time
Whether it is a personal loan or a student loan in Singapore, late repayment can significantly hurt your credit score. This is why you should always pay the debts in line with the agreement with the loan provider. If there are challenges in repaying the loan, do not let the delay go beyond 30 days because it is likely to get reported to the bureau.
Go for debt consolidation plans
If you find yourself engulfed by multiple debts, managing them can be challenging. Imagine having to juggle between five different debts, including high-interest credit card loans, alongside other regular chores. There is a risk of forgetting some, getting late with the monthly remittance, and incurring heavy penalties. If not addressed promptly, this problem can easily spiral and start affecting your score. To address this, you can consider a debt consolidation plan in Singapore.
Debt consolidation plans entail taking another loan to repay the existing debts so that you are left with only one debt. Remember that it does not in any way cut the total amount of debt. Instead, it only wraps them into one manageable loan. One payment is easier to keep up with, and paying on time is what supports your score over time.
Pay your bills on time
Although most bills, such as utility bills, are not reported to the credit bureaus when paid on time, they can easily find their way if you lag behind. For example, a library fee that goes unnoticed can easily make its way to the report if it is referred to a collection agency. So, once you incur a debt, be it for a utility at home or office, paying on time can help avoid damage to your score.
Other important considerations are maintaining a healthy credit mix, avoiding making multiple loan applications in quick succession, and limiting the number of credit cards to one or just a few.
Why you should apply for a loan in Singapore through Lendela
As you can see, maintaining your credit score at its best is crucial for good financial health. One of the methods we have highlighted to help you improve the score is taking up shorter loans and repaying them to rebuild a positive history.
Indeed, you should not shy away from other types of credit, be it car loans or renovation loans in Singapore. What you require is to have a good repayment strategy and to use Lendela, a loan matching platform in Singapore.
Lendela was designed to help simplify the process of the loan application. Instead of making multiple loan applications, which have a higher risk of getting rejected, you can use Lendela, which is simple and fast. The process can be broken down into four steps:
Visit Lendela’s website to submit a short application. Your application is forwarded to different banks and financial institutions simultaneously.
The loan providers come back with their offers, which are presented to you in your Lendela account.
You select the preferred offer and book an appointment with the selected loan provider online.
Sign the loan agreement and the funds are deposited to your bank account after the loan provider’s final checks.
Do not let your credit score slip down because it is likely to have a huge impact on your finances and entire life. Therefore, you need to rethink your life by staying on top of your budget. When applying for loans, use a trusted platform such as Lendela. Then, repay the loan on time.
Frequently asked questions
How much does a CBS credit report cost?
A standard CBS credit report costs $8 before GST, which is $8.72 with the current 9% GST.
How do I check my credit score in Singapore?
Buy your credit report from Credit Bureau Singapore online. The report shows your credit score and risk grade. You can also get a free report when you apply for a new credit facility, such as a personal loan, car financing or wedding loan.
What is a good credit score in Singapore?
CBS scores run from 1,000 to 2,000. A score of 1,911 to 2,000 earns the best grade, AA. The lowest grade, HH, covers 1,000 to 1,723.
Sources
Credit Bureau Singapore – https://www.creditbureau.com.sg/business-policy.html
Last updated: 11 October 2026.
The Lendela Team
Lendela is a loan-matching platform that partners with 70+ banks and financial institutions. We aim to deliver a transparent, safe, and personalised loan-matching experience, empowering borrowers with confidence to choose what truly fits. Since launching in 2018, we’ve helped hundreds of thousands of Singaporeans make smarter, more informed financial decisions through clarity and control.