


We show you every offer, every fee, every term, before you decide anything.
Since 2018, we've matched 340,000+ applications with 70+ banks & financial institutions — for weddings, renovations, debt consolidation, and everything in between.

Reverse Auction: Loan providers bid to give you their lowest rates
Compare & Save: Choose the best offer for your budget
Expert Help: Dedicated support from start to finish
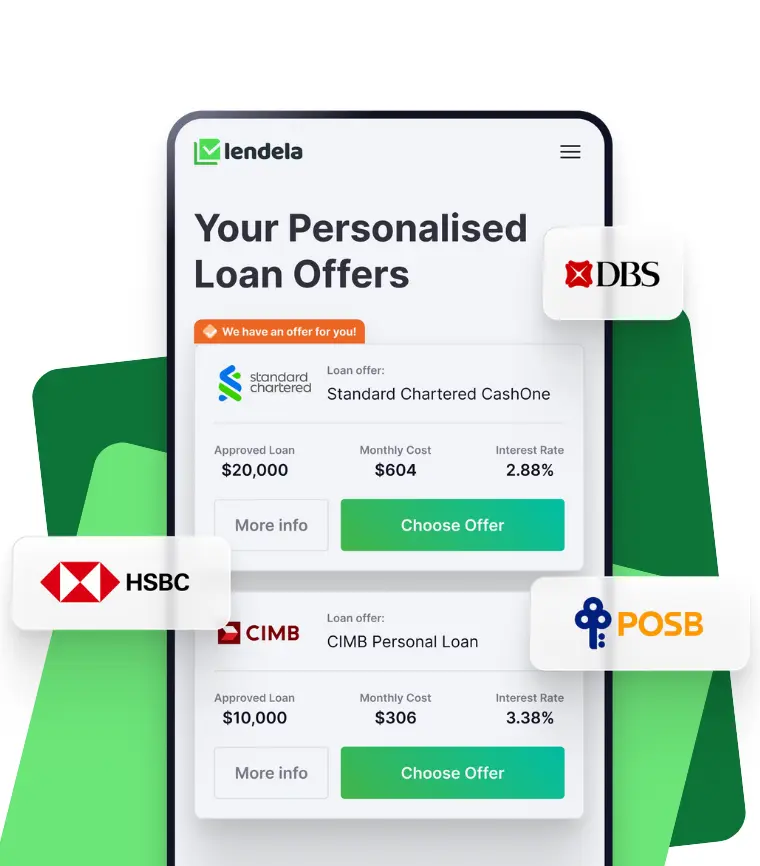
Personalised rates vary by income, residency status, employment stability, existing obligations, and repayment period.
Use this page to compare offers on the same tenure. For a full breakdown of current indicative rates by bank, including EIR and fees, see our personal loan interest rates comparison guide.
I want to borrow
$1,000
$200,000
and repay within
months
1 month
72 months
* For a loan amount of $20,000, APR of 6.95%, 5 year tenure, the tot. loan payable will be $26,940 with a monthly cost of $449. An individualised APR will be presented at the end of your application. Max. APR 48%. Min. repayment period 3 months, max. 72 months.
** Your final loan amount and repayment may vary based on income eligibility criteria. For CIMB Personal Loan, the maximum approved loan amount may be capped at $3,000 if your monthly income is below $2,000.
From
Monthly repayment
Apply once. See every offer from our loan provider panel, side by side. Our service is absolutely free — figure out the best repayment schedule you need or the right loan amount needed for your personal needs.
LEARN MORE
Hear what Singaporeans are saying about Lendela.


We show you every offer, every fee, every term, before you decide anything.
Since 2018, we've matched 340,000+ applications with 70+ banks & financial institutions — for weddings, renovations, debt consolidation, and everything in between.


For a clean personal loan comparison, compare offers in this order:
1. EIR / APR
2. Monthly repayment
3. Total payable amount
4. Processing, admin, late, and variation fees
5. Early repayment/redemption terms
6. Eligibility fit, such as income, residency status, employment stability, and credit profile
Compare offers on the same tenure first. If you compare a 12-month offer with a 60-month offer, the monthly repayment may look lower, but the total cost can be very different. If you want to apply this checklist to a real offer, read our guide on how to read a personal loan offer in Singapore. If you want to understand why EIR matters before you compare, read our guide to EIR in personal loans. If you are still deciding whether a personal loan is even the right product for your situation, start with our guide to loan types & when to use them.
Compare them over the same tenure on total payable, not on the flat rate. Example, hypothetical: $20,000 over 24 months. Offer C charges 1.00% flat plus a 3% fee: $1,000 in interest and fees, EIR 4.98%. Offer D charges 1.48% flat with no fee: $592, EIR 2.85%. Offer D is $408 cheaper despite the higher headline rate.
Processing/admin fees
Early repayment/redemption fees
Late payment fees
Contract variation fees (e.g. tenure or payment date changes)
Best practice: compare by total payable amount (principal + interest + fees)
Need help seeing how these fees show up inside a real offer? Read our guide on how to read a personal loan offer in Singapore. Need a quick glossary for EIR, APR, processing fees, late fees, and early repayment penalties? Read loan cost & pricing.
Use EIR/APR for apples-to-apples comparison. A low headline/flat rate can still cost more once fees and repayment mechanics (reducing balance) are accounted for. If you want a fuller explanation of how EIR works in Singapore, read our EIR guide. If you want a broader glossary for EIR, advertised rate, APR, flat vs. reducing-balance interest, and common borrowing fees, read loan cost & pricing.
Advertised rates are typically best-case. Actual pricing is driven by factors like monthly income, employment stability, existing loan obligations, and credit profile – so personalised offers are decision-grade.
There is no single personal loan rate that applies to everyone in Singapore. Advertised rates are usually best-case. The rate you actually receive depends on factors such as income, credit profile, existing obligations, residency status, and repayment period.
Use average-rate articles as background only. For real decision-making, compare the EIR/APR, monthly repayment, total payable amount, and fees across your personalised offers. If you want the fuller context, read our breakdown of average personal loan interest rates in Singapore.
It can. Multiple applications may create higher enquiry activity, which some banks and financial institutions interpret as higher risk. Do your comparison in a controlled way, then proceed when the terms fit.
Optimise for affordability and structure: a monthly repayment you can sustain, a tenure that doesn’t inflate total cost unnecessarily, and fee terms that won’t punish you later. Bigger isn’t automatically better. If you want a deeper explanation of borrowing limits and what affects approval, read our guide to how much you can borrow for a personal loan in Singapore.
There’s no universal best: shorter tenure usually lowers total interest but raises monthly repayment; longer tenure lowers monthly repayment but increases total interest. Compare 2–3 tenures and decide based on affordability and total payable amount.
At Lendela, you apply once to view a variety of personalised offers, making your loan comparison clear and transparent when it comes to terms. It also eliminates repeated form submissions and trial-and-error applications, which is positive for your credit score.
MoneySense: costs of borrowing – https://www.moneysense.gov.sg/costs-of-borrowing-flat-rate-monthly-rest-and-effective-interest-rate/
MoneySense: understand the types of loans – https://www.moneysense.gov.sg/understand-the-types-of-loans/
Note: Personalised offers vary by profile, repayment period, fees, and bank policy. Compare EIR/APR, monthly repayment, and total payable amount before choosing.
From rate movements to practical money tips, get the updates that keep you informed, whenever they’re worth sharing.
You're subscribed.
We'll send Lendela's money tips and updates to .
