A business loan is financing provided to your company rather than to you personally, used for cash flow, growth, or equipment.
Apply once through Myinfo Business and get matched with offers from 70+ MAS-licensed lenders. Review tenure, fees and total cost side by side.
Supported by:
Lump-sum financing for cash flow, payroll, rent, inventory, marketing, and expansion – repaid over a fixed repayment tenure with clear monthly instalments.
Unlock working capital by financing outstanding invoices – useful when payments are pending and you need to bridge short-term cash flow gaps.
For eligible SMEs, EFS-WCL supports working capital needs. Approval checks may include group annual sales, employment size, and corporate structure.
Share your purpose, amount, and company details via Myinfo Business and ACRA retrieval. This helps us match you with the most relevant and competitive offers, with reduced back-and-forth along the process.
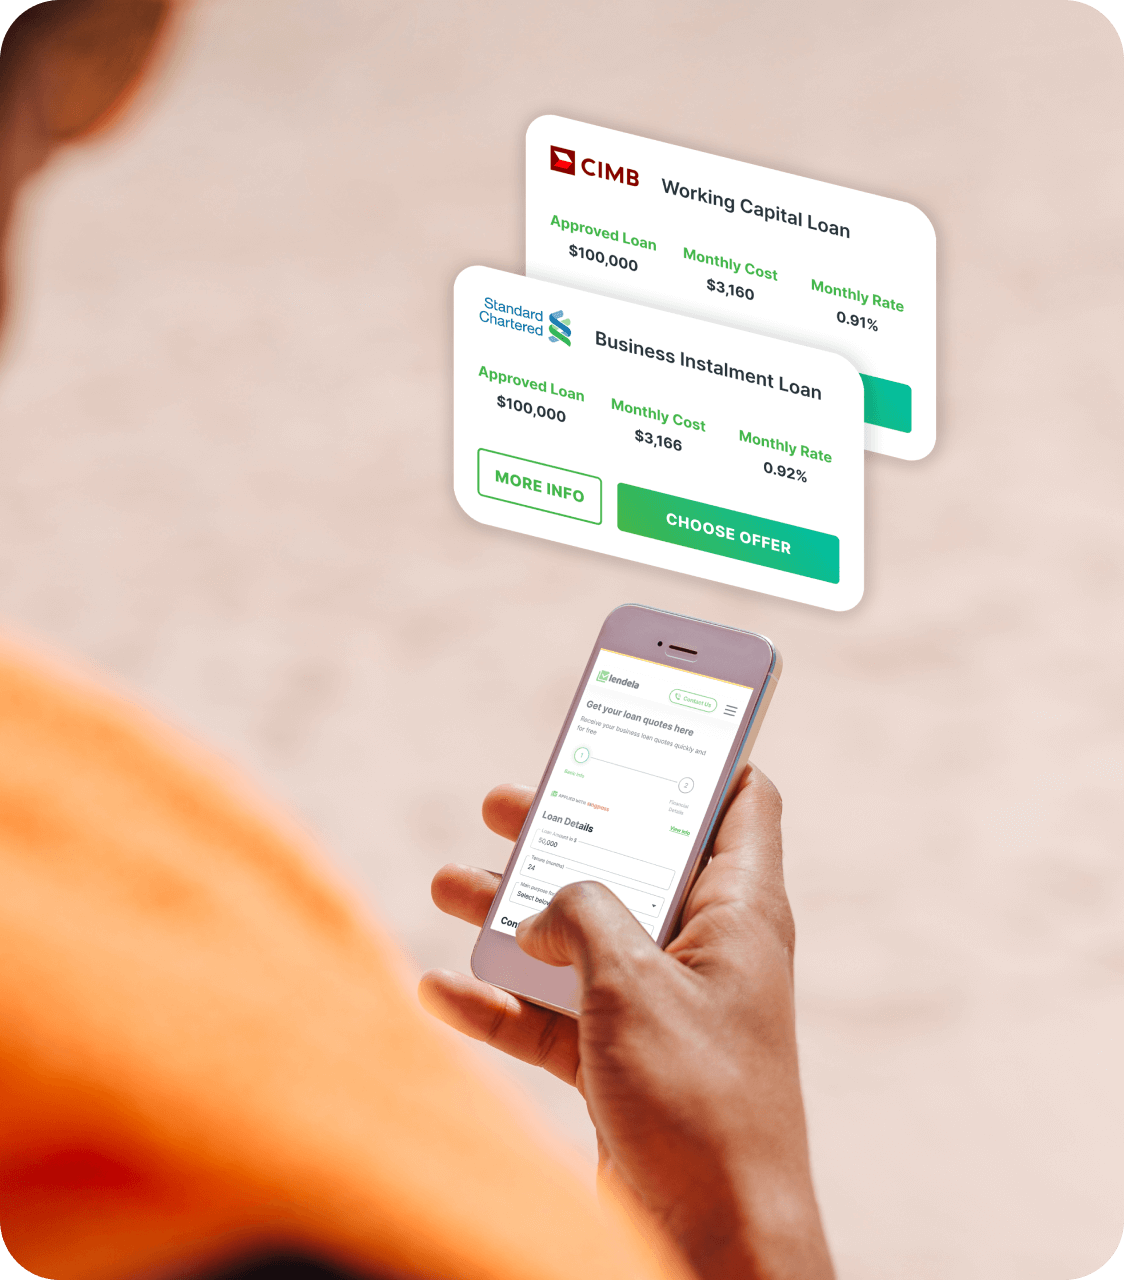
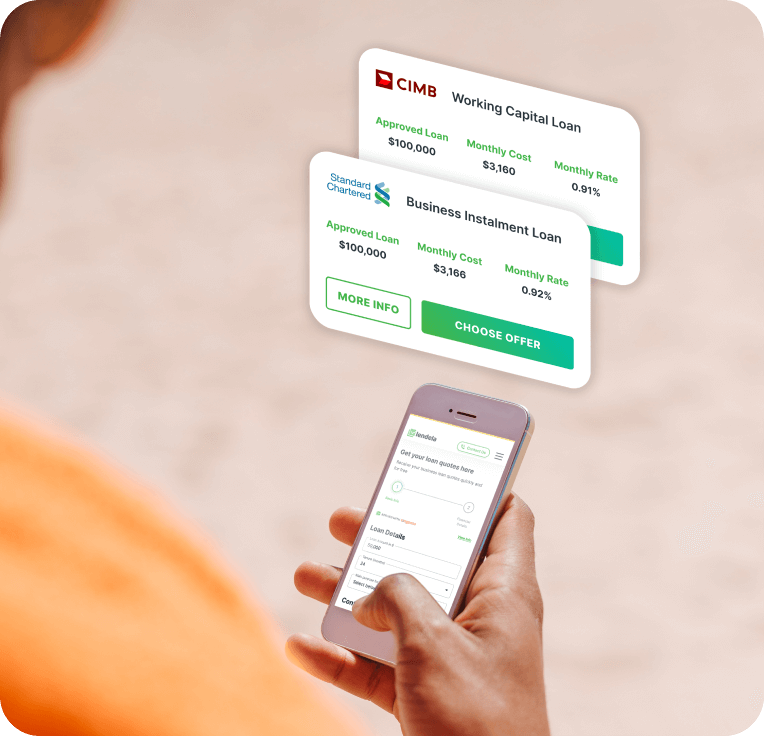
Match with tailored, pre-approved loan offers from banks and financial institutions. See key terms in one view – repayment tenure, fees, and indicative total cost – so you can choose confidently.
Choose the most suitable offer and finalise the agreement with the bank to receive your funds. That's it! It’s a simple, guided process designed to make securing your business loan easy and worry-free.
Banks and financial institutions bid based on your company's actual financials, not a generic profile. You choose based on total cost and fit, not who has the loudest ad.
Repayment tenure, fees, and total payable, compared side by side — including guarantor requirements that often surface late and stall an approved offer.
Apply once through Myinfo Business and ACRA retrieval. See offers from banks and financial institutions side by side, without resubmitting the same documents twice.
Every application is reviewed by our team before it reaches a lender. Shareholding and group-structure issues get caught before they cost you an approved offer.
S$300 million disbursed, over S$66 million saved in interest versus the highest offer on our panel, across 340,000+ applications.
2572 Reviews
Take the first step towards securing funding. Request for loan quotes today.
GET LOAN QUOTESUnsure about the process or have any doubts? We’re happy to share more about the business loan process and structuring.
A business loan is financing provided to a company, rather than an individual, to support cash flow, expansion, equipment purchases, or day-to-day operations. In Singapore, this includes unsecured working capital and term loans, government-assisted schemes such as EFS-WCL, invoice financing, and secured facilities such as equipment or commercial property loans.
The right type depends on your business's size, trading history, and what the funds are for. Lendela matches eligible SMEs with 70+ MAS-licensed lenders through a single application.
Businesses commonly consider:
Working capital/term loans (unsecured)
Government-assisted SME loans (e.g. EFS-WCL, if eligible)
Invoice financing
Equipment/machinery financing (secured)
Trade finance
Commercial property loans
EFS-WCL is an Enterprise Singapore scheme that supports SMEs financing operational cashflow needs. Key published criteria include:
Entity registered and operating in Singapore
At least 30% local equity held directly/indirectly by Singapore citizens/PRs
Group annual sales turnover not exceeding $500m
For “SME Working Capital”, SME defined as group revenue up to $100m or maximum group employment size of 200
Loan details published by EnterpriseSG include maximum loan quantum $500,000 per borrower, capped at $5,000,000 per borrower group, and maximum repayment period 5 years. Government risk-share is 50%, rising to 70% for young enterprises under 5 years old. This reduces the bank's risk, not what you repay. (Terms apply; final approval is by participating financial institutions.)
For some government-assisted scheme assessments, borrower group definitions can include the borrower, corporate shareholders holding more than 50%, and relevant subsidiaries in the ownership chain. This is why banks and financial institutions may ask for group structure and consolidated figures.
Requirements vary, but common documents include:
ACRA BizFile/company profile
Directors/guarantors IDs (and shareholding/structure where relevant)
Latest 3–6 months business bank statements
Latest financial statements (if available)
Tax filings/Notices of Assessment (NOAs), where applicable
Existing debts schedule (outstanding facilities + monthly obligations)
Use-of-funds statement (1–2 paragraphs)
It depends on revenue, profitability, recent bank statements, existing debts, and guarantor strength. For EFS-WCL specifically, EnterpriseSG publishes a maximum loan quantum of $500,000 per borrower, capped at $5,000,000 per borrower group (subject to scheme and bank assessment).
Focus on:
Interest pricing (e.g. EIR/APR where applicable)
Processing/admin fees
Late charges/default interest
Early repayment terms
Best practice: compare total payable amount across the same repayment tenure, then read the terms and conditions before acceptance.
With complete documents, expect a few days in general; some digital-first banks and financial institutions can be faster when they handle straightforward cases.
When the financing supports cash-generating investments (such as inventory, working capital gaps, equipment investment, further expansion etc.) and monthly repayments remain sustainable even during slower months.
Yes, startups can apply, but the range of available options may be more limited and interest rates slightly higher, since banks assess risk based on trading history and cash flow.
Under the EFS, “young enterprises” – defined as businesses less than 5 years old, with at least one employee and over 50% individual ownership – may qualify for a higher risk-share of up to 70%.
However, approval still depends on the lender’s credit assessment and documentation review.
Tip: Having clear financial projections and up-to-date bank statements can help strengthen a startup’s loan application.
For company-use funds, business financing keeps liabilities ring-fenced and builds entity banking history. Personal loans can be faster but may blur personal vs. business obligations.
From rate movements to practical money tips, get the updates that keep you informed, whenever they’re worth sharing.
You're subscribed.
We'll send Lendela's money tips and updates to .