
The Lendela Team
December 1st, 2026
Table of contents
- Waiting for the perfect moment to borrow can pay off or cost you. Interest rates cannot be read in advance, but your age can.
- Three-month SORA fell from 3.59% to 1.15% between the third quarters of 2024 and 2026, yet home loan rates in the market were below 1.5% in 2020 to 2021 and above 4% in 2022 to 2023.
- For an HDB loan, the repayment period is the shortest of 25 years, 65 minus the buyers' average age, or the remaining lease minus 20 years. Until the average age reaches about 40, waiting does not shorten it.
- On a $400,000 loan at 2.6%, the monthly instalment is about $1,815 over 25 years, $2,139 over 20 years and $2,686 over 15 years (an illustration, as at November 2026).
- The CPF Board suggests keeping $20,000 in your OA as an emergency fund, which would grow to about $39,700 in 20 years.
Waiting for the perfect moment to take a home loan can save you money or cost you. The difference comes down to two things: one you cannot read and one you can. Interest rates cannot be read. Three-month SORA, the benchmark published by the Monetary Authority of Singapore (MAS), fell from 3.59% in Q3 2024 to 1.15% in Q3 2026. Yet the CPF Board notes that home loan rates in the market were below 1.5% in 2020 to 2021 and above 4% in 2022 to 2023.
Age can be read. For an HDB loan, the repayment period is the shortest of 25 years, 65 minus the buyers' average age, or the flat's remaining lease minus 20 years. Until the average age reaches about 40, waiting does not shorten it. On a $400,000 loan at 2.6%, the monthly instalment rises from about $1,815 over 25 years to about $2,686 over 15 years (an illustration, as at November 2026).
Waiting also buys something. The CPF Board suggests keeping $20,000 in your Ordinary Account (OA) as an emergency fund while you repay, and a larger downpayment reduces the loan itself. This guide sets out what waiting can cost, what it can buy, and how to tell patience from avoidance.
What does a ten-year voyage have to do with waiting?
Odysseus spent ten years fighting at Troy and ten more trying to get home to Ithaca. Christopher Nolan's film retold the story this July, but it is Homer's poem that matters here.
Early on, the god of the winds gave him a bag of winds to carry him home. With Ithaca in sight, Odysseus slept, and his crew, sure the bag held treasure, opened it. The winds blew them all the way back: a good wind, lost within sight of the shore.
Later, held on an island by bad winds, the crew ran out of food, ate the cattle of the sun god, and Zeus destroyed their ship. Odysseus washed up on Calypso's island and stayed seven years in comfort. With a year spent earlier on Circe's island, eight of his ten years passed on two islands. When he finally left, it was on a raft, with food and drink from Calypso, and he reached Ithaca alone.
Three things in that story appear whenever someone waits for the perfect moment to borrow: a wind nobody can read, a clock that keeps running, and what you carry while you wait. The next sections take each in turn.
Can you wait for interest rates to fall?
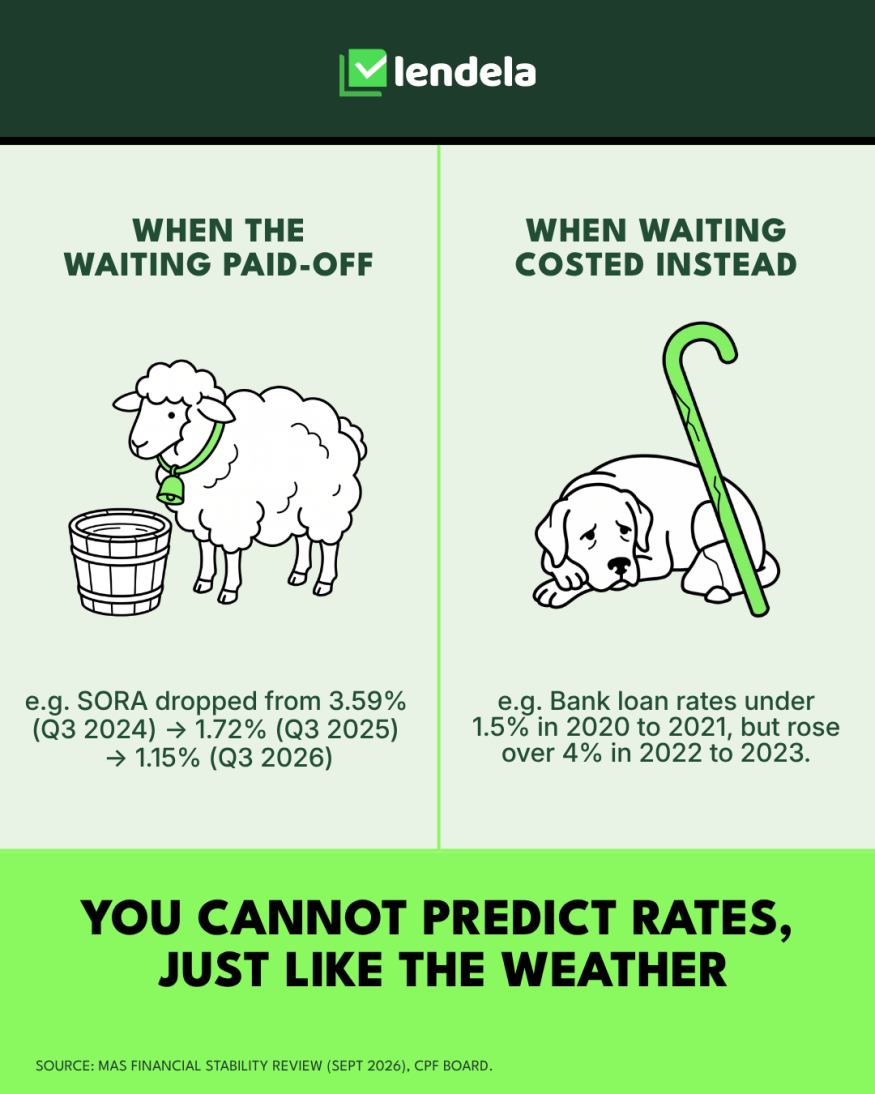
Nobody can read interest rates in advance, and the recent past shows waiting working in both directions.
Period | What happened | Source |
|---|---|---|
Q3 2024 to Q3 2026 | Three-month SORA fell from 3.59% to 1.72% (Q3 2025) to 1.15% | MAS Financial Stability Review, September 2026 |
Q2 2025 to Q2 2026 | The median interest rate on new mortgages fell by about 100 basis points | MAS Financial Stability Review, September 2026 |
2020 to 2021, then 2022 to 2023 | Home loan rates in the market were below 1.5%, then above 4% | CPF Board |
Waiting paid for anyone who held off through 2024 to 2026.
Waiting cost for anyone who held off in 2021 hoping for lower rates.
MAS's September 2026 review advises households to build adequate liquidity buffers.
We do not predict rates, and nobody could have called either swing in advance.
What does waiting do to your HDB loan repayment period?
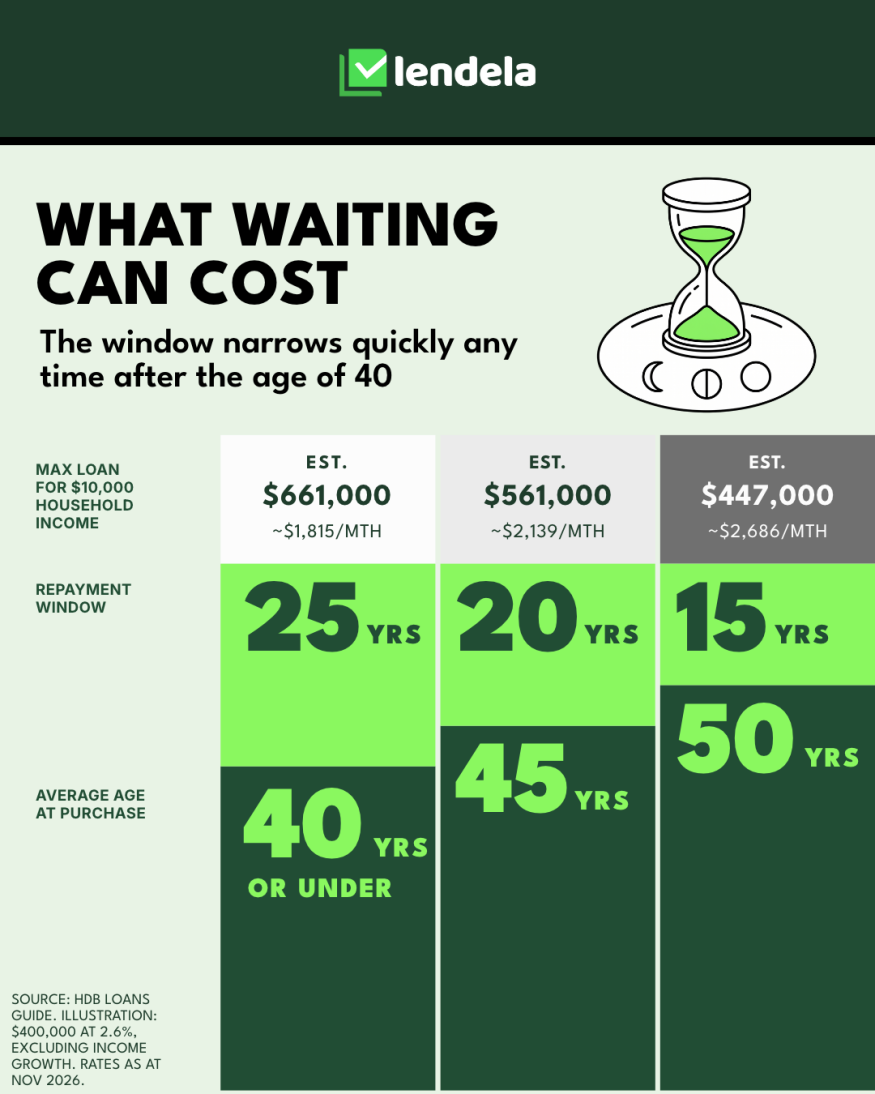
Your age is the part of the decision you can read. HDB caps the repayment period of its housing loan at the shortest of 25 years, 65 minus the average age of the buyers, or the flat's remaining lease minus 20 years. Monthly instalments are limited to 30% of your monthly income.
Average age at purchase | Repayment period | Monthly instalment on $400,000 at 2.6% | Total interest | Maximum loan at $10,000 household income |
|---|---|---|---|---|
40 or under | 25 years | about $1,815 | about $144,000 | about $661,000 |
45 | 20 years | about $2,139 | about $113,000 | about $561,000 |
50 | 15 years | about $2,686 | about $84,000 | about $447,000 |
Illustration only: $400,000 at the HDB loan rate of 2.6%, as at November 2026, excluding income growth and HDB's own loan-sizing assessment. Maximum loan assumes a monthly repayment of 30% of $10,000.
Until about 40, waiting does not shorten the window. The 25-year cap holds until the buyers' average age passes 40.
After 40, each year narrows it by a year. At an average age of 45 the cap is 20 years, and at 50 it is 15 years.
Total interest falls as the period shortens, so waiting moves the cost into the monthly bill and your borrowing capacity, not necessarily into the total you repay.
A loan from a bank or financial institution can run up to 30 years, compared with up to 25 years for an HDB loan. Bank loan terms and limits vary, so check with your bank.
For how the 30% and 55% limits work, read our guide to MSR and TDSR, or estimate your own limit with the HDB affordability calculator.
What should you carry while you wait?
Whether waiting is patience or a gamble depends on what you carry while you do it.
$20,000 in your CPF OA. If you buy a flat with an HDB loan, you use your OA savings first, but the CPF Board says you may keep up to $20,000 in your OA and recommends it as an emergency fund. It earns up to 3.5% a year and would grow to about $39,700 in 20 years.
Three to six months of expenses. MAS cites a three-to-six-month savings buffer as a benchmark in its September 2026 Financial Stability Review.
A cushion for a shock. In MAS's stress test, about 1% of borrowers could face negative cash flow if their savings cover less than six months of expenses.
A small gap between owing and earning. The HDB loan rate of 2.6% is pegged at 0.1 percentage point above the OA rate, so for buyers using an HDB loan the gap between what the loan costs and what the OA earns is small.
A national cushion. MAS reports that household cash and deposits continued to exceed total household liabilities in the second quarter of 2026.
What is the opportunity cost of waiting to borrow?
Opportunity cost is what the waiting time could have been used for. Odysseus is the clearest example: eight of his ten years went on two islands, years he could have spent at home. For a loan, it works in two directions.
What waiting can give you | What waiting can cost you |
|---|---|
A bigger downpayment. Each extra $10,000 put down lowers a 25-year loan at 2.6% by about $45 a month and avoids about $3,600 in interest | Months or years in the home you could have had, and rent paid in the meantime (not priced here) |
A fuller buffer. $20,000 in the OA grows to about $39,700 in 20 years | A shorter repayment period after about age 40 |
Time for rates to move | Rates can move the other way, as between 2021 and 2022 |
The $45 and $3,600 figures are an illustration at 2.6% over 25 years.
The left column is priced, and the first row of the right column is not. We cannot put a figure on rent or on where property prices go, so we do not. The test is whether what you gain by waiting is worth more than what you give up, and that depends on your household. For a sense of how loan size follows income, see HDB affordability by salary.
So, when is the right timing?
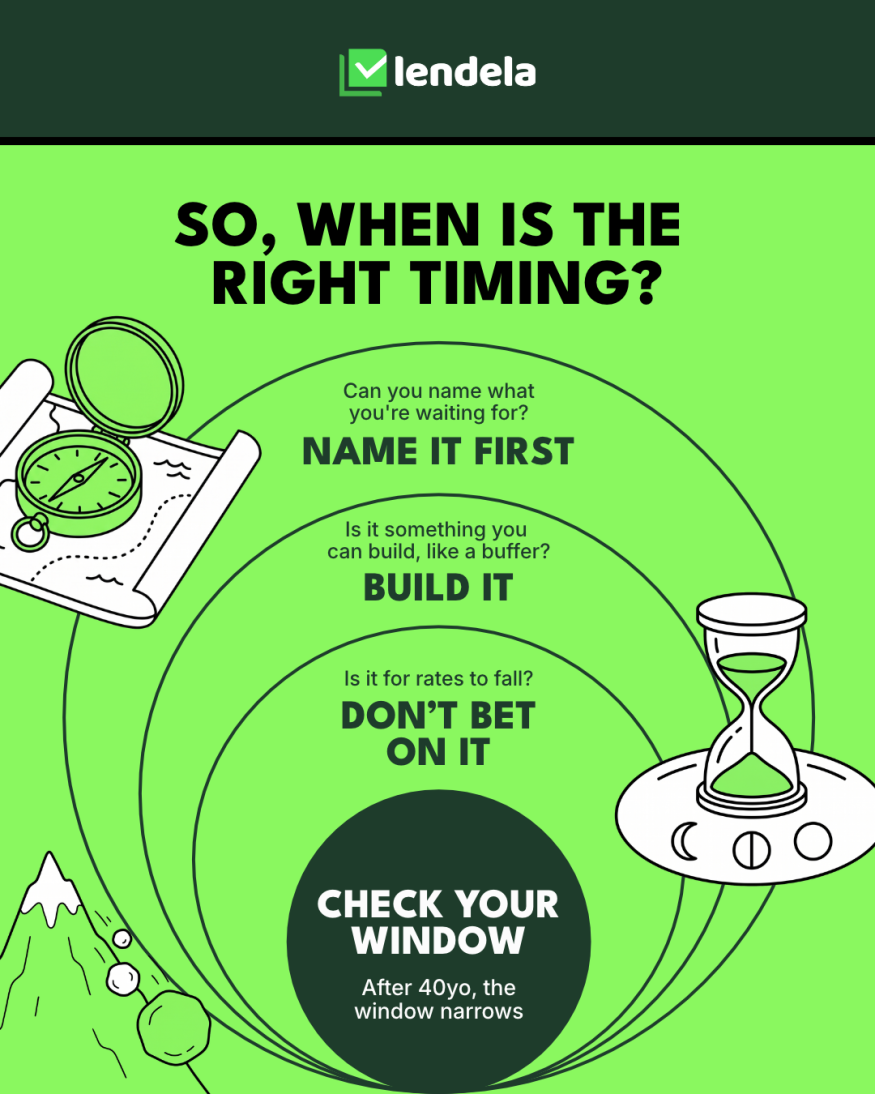
No single answer fits every household, but three questions help sort the decision.
Question | If the answer is | Then | The one fact |
|---|---|---|---|
Can you name what you are waiting for? | No | Name it first | A number, a date or a milestone turns waiting into a plan |
Is it something you can build, like a buffer? | Yes | Build it | CPF suggests keeping $20,000 in your OA |
Is it for rates to fall? | Yes | Do not bet on it | Home loan rates were below 1.5% in 2020 to 2021 and above 4% in 2022 to 2023 |
None of the above | Check your window | After about 40, the repayment period narrows |
None of this means a loan is the answer. If you are considering one, the aim is to decide on the numbers, not the calendar.
Where can you check your own numbers?
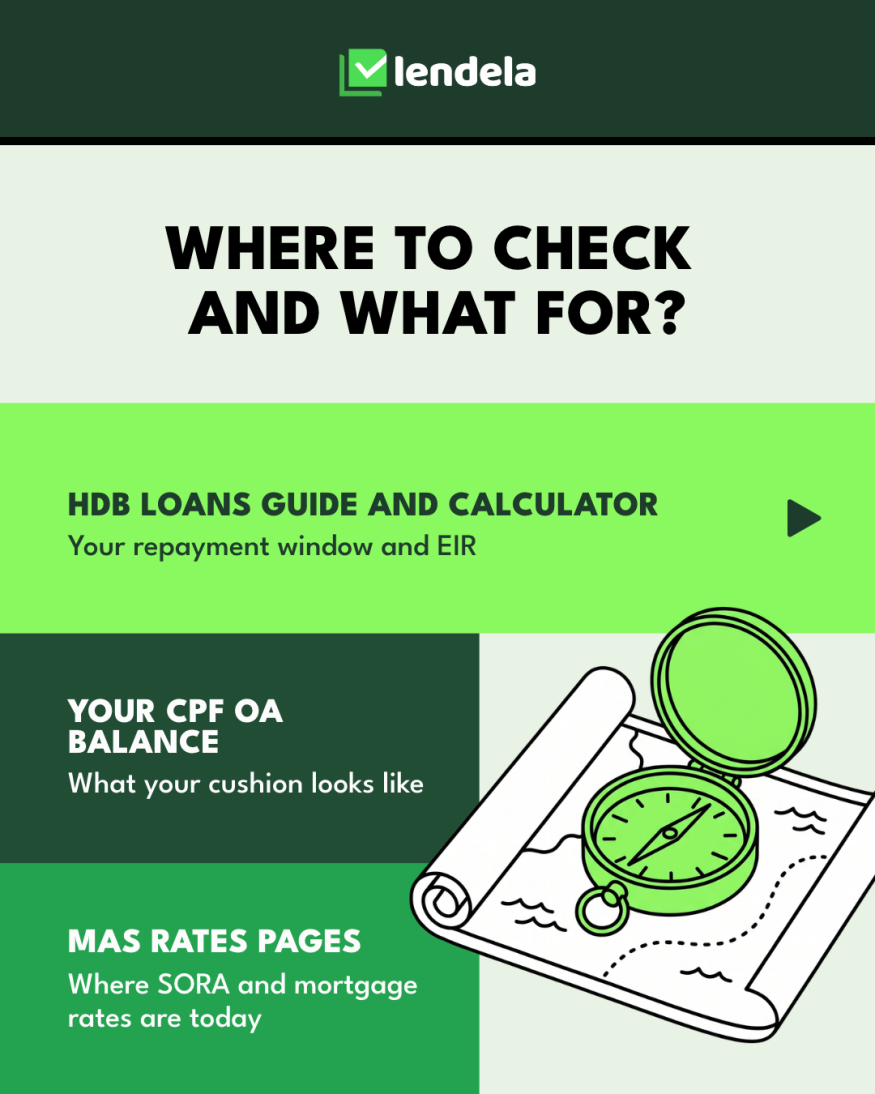
Where to check | What you will find |
|---|---|
Your repayment period, the HDB loan rate and the 30% instalment limit | |
What your OA cushion could look like | |
Where SORA and mortgage rates stand | |
Any bank loan quote | The effective interest rate (EIR), which includes fees |
What else is worth knowing before you wait?
A shorter repayment period lowers total interest. On the same $400,000 loan, interest falls from about $144,000 at 25 years to about $84,000 at 15, but the monthly instalment rises by about $871 (an illustration at 2.6%).
The HDB loan rate follows the OA rate. It is pegged at 0.1 percentage point above it, so the two move together.
A choice made in advance can help. In Homer's poem, Odysseus has himself tied to the mast to sail past the Sirens. In a study of commitment savings accounts in the Philippines, Ashraf, Karlan and Yin (2006) found that 28.4% of people offered one opened it, and after twelve months average savings balances were 81 percentage points higher for those offered the account than for those who were not.
What if you are considering a loan?
If you are considering a loan, Lendela's loan matching platform lets you submit one application and see personalised offers from 70+ banks and financial institutions, at no cost and with no impact on your credit score. Compare personalised loan offers when you are ready. Rates shown are personalised estimates, so check the total repayment and tenure before you decide.
The same exercise works for other everyday costs. We have added up what subscriptions really cost and the real price of 11.11.
Get Your Loan Options
Find tailored offers in minutes — free to check, with no impact on your credit score.
Frequently asked questions
Should I wait for interest rates to fall before taking a home loan in Singapore?
It depends, because nobody can read rates in advance. Three-month SORA fell from 3.59% to 1.15% between the third quarters of 2024 and 2026, but the CPF Board notes home loan rates in the market were below 1.5% in 2020 to 2021 and above 4% in 2022 to 2023. Waiting helped some borrowers and cost others, so it helps to decide on what you can afford, not on a rate forecast.
Does my age affect the HDB loan repayment period?
Yes. HDB caps the repayment period at the shortest of 25 years, 65 minus the buyers' average age, or the flat's remaining lease minus 20 years. If the average age is 40 or under, age does not shorten the 25-year cap. At an average age of 45, the cap is 20 years.
What is the maximum repayment period for an HDB loan?
Up to 25 years, or less where the buyers' average age or the flat's remaining lease requires. A loan from a bank or financial institution can run up to 30 years, according to HDB. Bank loan terms and limits vary, so check with your bank.
Does waiting to buy a home change the total interest I pay?
Not necessarily. A shorter repayment period lowers total interest but raises the monthly instalment. On a $400,000 loan at 2.6%, total interest is about $144,000 over 25 years and about $84,000 over 15, while the monthly instalment rises from about $1,815 to about $2,686 (an illustration).
How much should I keep in my CPF OA when buying a home?
The CPF Board says you may keep up to $20,000 in your OA when you buy a flat with an HDB loan, and recommends it as an emergency fund. It earns up to 3.5% a year and would grow to about $39,700 in 20 years. Check the CPF Board for the rules that apply to your purchase.
What is SORA and why does it matter for home loans?
SORA, the Singapore Overnight Rate Average, is a benchmark interest rate published by MAS. Floating-rate home loans in Singapore are commonly priced against it, so when SORA moves, the interest on those loans can move too. Three-month SORA was 1.15% in the third quarter of 2026, according to MAS.
What is a commitment device, and can it help with saving?
A commitment device is a choice you make in advance that limits what you can do later. In a study of commitment savings accounts in the Philippines, 28.4% of people offered one opened it, and savings balances were 81 percentage points higher after twelve months for those offered the account. It works like Odysseus having himself tied to the mast: the decision is made before the temptation arrives.
Sources
Monetary Authority of Singapore, MAS Financial Stability Review (September 2026)
Housing & Development Board, HDB housing loans guide
CPF Board, HDB or bank loan: 3 differences
CPF Board, How much CPF OA should you use when buying your first home
Ashraf, N., Karlan, D. and Yin, W. (2006), Tying Odysseus to the Mast, Quarterly Journal of Economics 121(2): 635–672
Encyclopaedia Britannica, Odyssey
Deadline, The Odyssey review
Figures verified as at November 2026. Rates, regulations and scheme terms can change, and your own situation will differ, so please treat this as general information, not financial advice, and check directly with HDB, the CPF Board or your bank before making any decision. Loan figures are illustrations at the HDB loan rate of 2.6%, not Lendela rates.
The Lendela Team
Lendela is a loan-matching platform that partners with 70+ banks and financial institutions. We aim to deliver a transparent, safe, and personalised loan-matching experience, empowering borrowers with confidence to choose what truly fits. Since launching in 2018, we’ve helped hundreds of thousands of Singaporeans make smarter, more informed financial decisions through clarity and control.